Mortgage Rates Surge to Three-Year High Amid Global Bond Market Turmoil
MIAMI — October 1, 2026
Mortgage rates have surged to a three-year high as of October 1, 2026, reaching levels that could significantly impact home buyers and the broader real estate market. This development comes in the wake of a global bond market selloff, which has sent ripples through financial markets and raised borrowing costs for consumers.
The current average mortgage rate has climbed sharply, with reports indicating it has surpassed 7% for the first time since 2023. This increase is attributed to a combination of factors, including rising inflation expectations and the Federal Reserve’s ongoing efforts to combat inflation through interest rate hikes. The Fed’s recent decision to maintain a hawkish stance on monetary policy has further exacerbated the situation, leading to increased yields on government bonds and, consequently, higher mortgage rates.
Key players in this scenario include the Federal Reserve, which has been actively managing interest rates to stabilize the economy, and various financial institutions that are adjusting their lending rates in response to market conditions. The implications of these rising rates are profound, particularly for first-time home buyers who may find themselves priced out of the market. According to data from the National Association of Realtors, the surge in rates could lead to a significant decline in home sales, as potential buyers reassess their purchasing power.
This development is receiving heightened attention now due to its potential to reshape the housing landscape. With affordability already a pressing issue in many markets, the increase in mortgage rates could lead to a slowdown in home price growth or even a decline in certain areas. Analysts are closely monitoring the situation, as a sustained period of high rates could dampen consumer confidence and lead to broader economic repercussions.
Locally, in Miami, where the real estate market has been characterized by rapid price increases, the impact of rising mortgage rates could be particularly acute. The city has seen a surge in demand for luxury properties, but as financing becomes more expensive, the dynamics of the market may shift. Nationally, the implications are equally significant, as the housing market is a critical component of the U.S. economy, influencing everything from consumer spending to employment rates in construction and related industries.
Looking ahead, it is realistic to anticipate that the Federal Reserve will continue to monitor economic indicators closely, potentially leading to further adjustments in interest rates. Home buyers may need to adapt to a new reality of higher borrowing costs, and real estate professionals will likely need to recalibrate their strategies in response to changing market conditions. As the situation evolves, stakeholders across the housing sector will be watching for signs of stabilization or further volatility in mortgage rates.
Source: Realtor.com
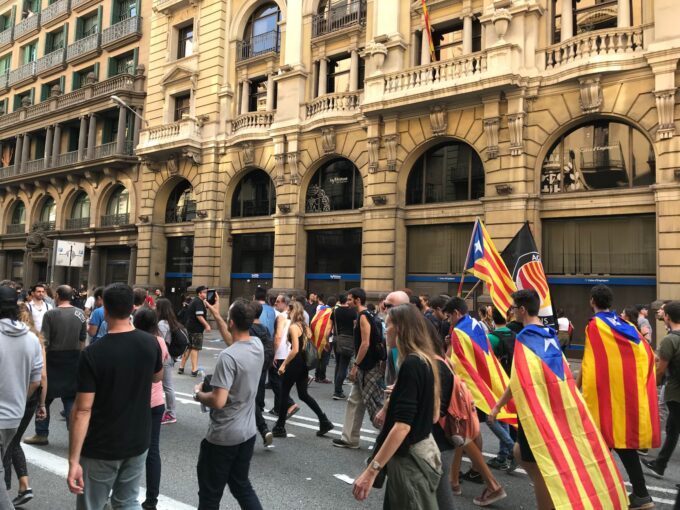
Protests Erupt in Spain Over Housing Crisis as Tenant Unions Demand Action
Mass protests in Spain highlight the urgent need for housing solutions amid...
 2 Mins read
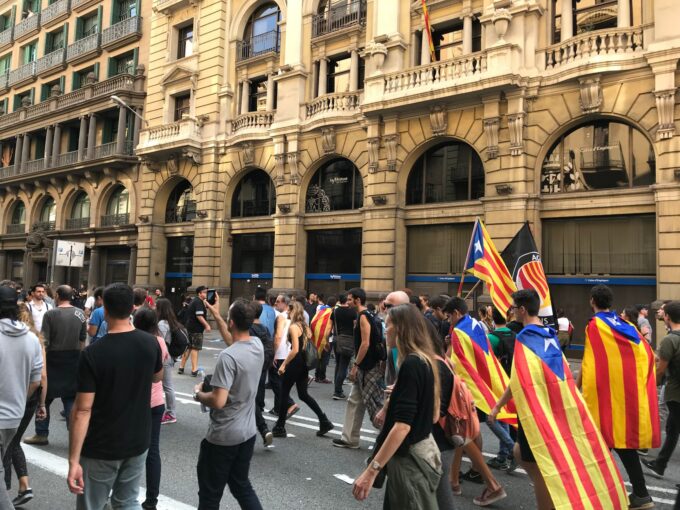
Protests Erupt Across Spain Over Housing Crisis Amid Rising Evictions
Hundreds of thousands take to the streets as Spain grapples with a...
2 Mins read
Nationwide Protests Erupt in Spain Following Eviction of Elderly Woman
Protests across Spain highlight urgent housing rights issues after the eviction of...
2 Mins read


Massive Protests Erupt in Spain Following Eviction of 87-Year-Old Woman
Tens of thousands of demonstrators took to the streets across Spain today...
2 Mins read

Leave a comment