
Understanding the Landscape of Long-Term Care in Miami
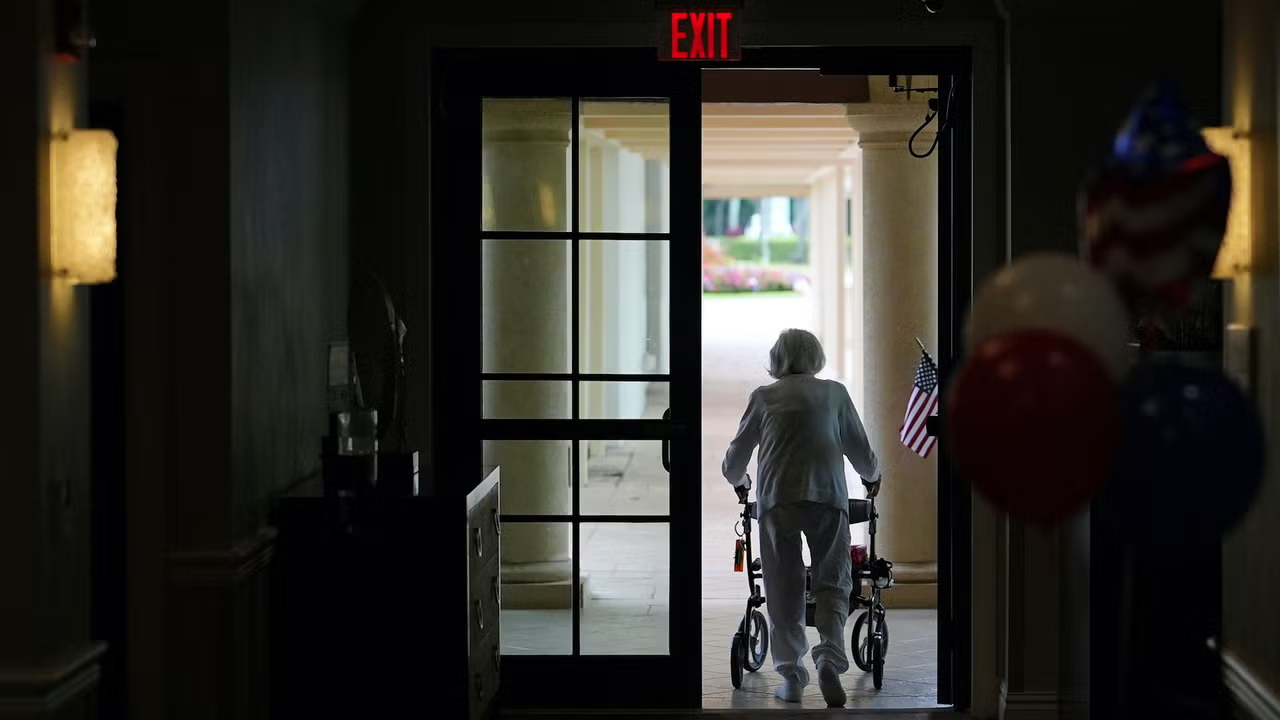
As Miami’s population ages and the demand for long-term care services increases, the financial implications of this trend become more significant. Planning for long-term care is not just about setting aside funds; it’s about making informed investment decisions that can safeguard your financial future. For the affluent residents of Miami, understanding the various avenues for investing long-term care funds is crucial.
The Case for Health Savings Accounts
While many may consider a Health Savings Account (HSA) as an ideal vehicle for long-term care expenses due to its tax-free withdrawals for qualified healthcare costs, there are nuances to consider. The annual contribution limits—set at $4,400 for individuals and $8,600 for families by 2026—can hinder significant capital growth, particularly for those over 50.
Moreover, the tax benefits associated with HSAs may not be fully utilized if long-term care costs are also deductible, potentially leading to less strategic financial planning. Although HSAs can benefit heirs, it’s essential to note that if the account is inherited by anyone other than a spouse, the tax advantages evaporate.
Leveraging Traditional IRAs for Optimal Tax Strategy
For strategic investors, traditional IRAs present a compelling alternative. Given that most retirement savings are held within these accounts, utilizing them for long-term care expenses can be advantageous. Withdrawals from a traditional IRA are taxable, but if these withdrawals coincide with high healthcare deductions, the tax burden may be alleviated significantly.
Individuals facing substantial long-term care costs often surpass the threshold for deductibility, which allows them to offset taxes on IRA withdrawals. As required minimum distributions kick in for those over 73, the strategic timing of withdrawals becomes paramount to minimize tax liabilities.
Investment Strategies: Balancing Growth and Risk
Investing for long-term care isn’t merely about choosing the right account; it’s also about smart asset allocation. For those in their mid-60s, the need for long-term care might be 15 years away, prompting a higher risk tolerance. Investing primarily in equities can yield the growth necessary to combat rising long-term care costs, which have been shown to outpace general inflation rates.
As one approaches their mid-70s, the timeline shortens, and it may become prudent to shift towards a more conservative mix of bonds and cash. This gradual transition helps to protect the fund as the need for long-term care becomes more imminent.
Proactive Financial Planning for Miami’s Affluent
For Miami’s business leaders and affluent residents, proactive financial planning is key to securing long-term care needs. Establishing a comprehensive strategy that includes diverse investment accounts, thoughtful asset allocation, and an understanding of tax implications can lead to a more comfortable retirement. With the rising costs of care and the unpredictability of health needs, preparing today means enjoying peace of mind tomorrow.
Conclusion: A Call to Action
Investing for long-term care requires a sophisticated understanding of financial instruments and market dynamics. By leveraging HSAs and traditional IRAs effectively and adopting a strategic approach to asset allocation, Miami’s elite can navigate the complexities of long-term care funding. As the market continues to evolve, staying informed and proactive will ensure that financial strategies remain robust and adaptable, securing a prosperous future for families.
Editorial note: This article was created by A Bit Lavish Miami’s Magazine as an original editorial reinterpretation based on publicly available reporting. Original source: fastcompany.com. Read the original article here: https://www.fastcompany.com/91595657/long-term-care-best-way-invest-money.
Images are used for editorial reference with source credit. If an image requires correction or removal, please contact A Bit Lavish.

Trump Announces ‘Super Intelligence Force’ for AI Oversight
The establishment of a new regulatory body for artificial intelligence marks a...
 2 Mins read
Sydney Sweeney’s Novig Ad Sparks Controversy and Boosts Company Valuation
Sydney Sweeney's recent advertisement for Novig has ignited backlash from female athletes...
2 Mins read
Maximizing Your iPhone: Unlocking Hidden Storage Without Sacrifice
Discover innovative ways to reclaim iPhone storage without deleting cherished memories or...
3 Mins read
Trump Announces Creation of ‘Super Intelligence Force’ to Oversee AI Policy
The establishment of the 'Super Intelligence Force' marks a pivotal shift in...
2 Mins read