US Mortgage Rates Surpass 7% for First Time in Nearly Two Years
MIAMI — September 25, 2026
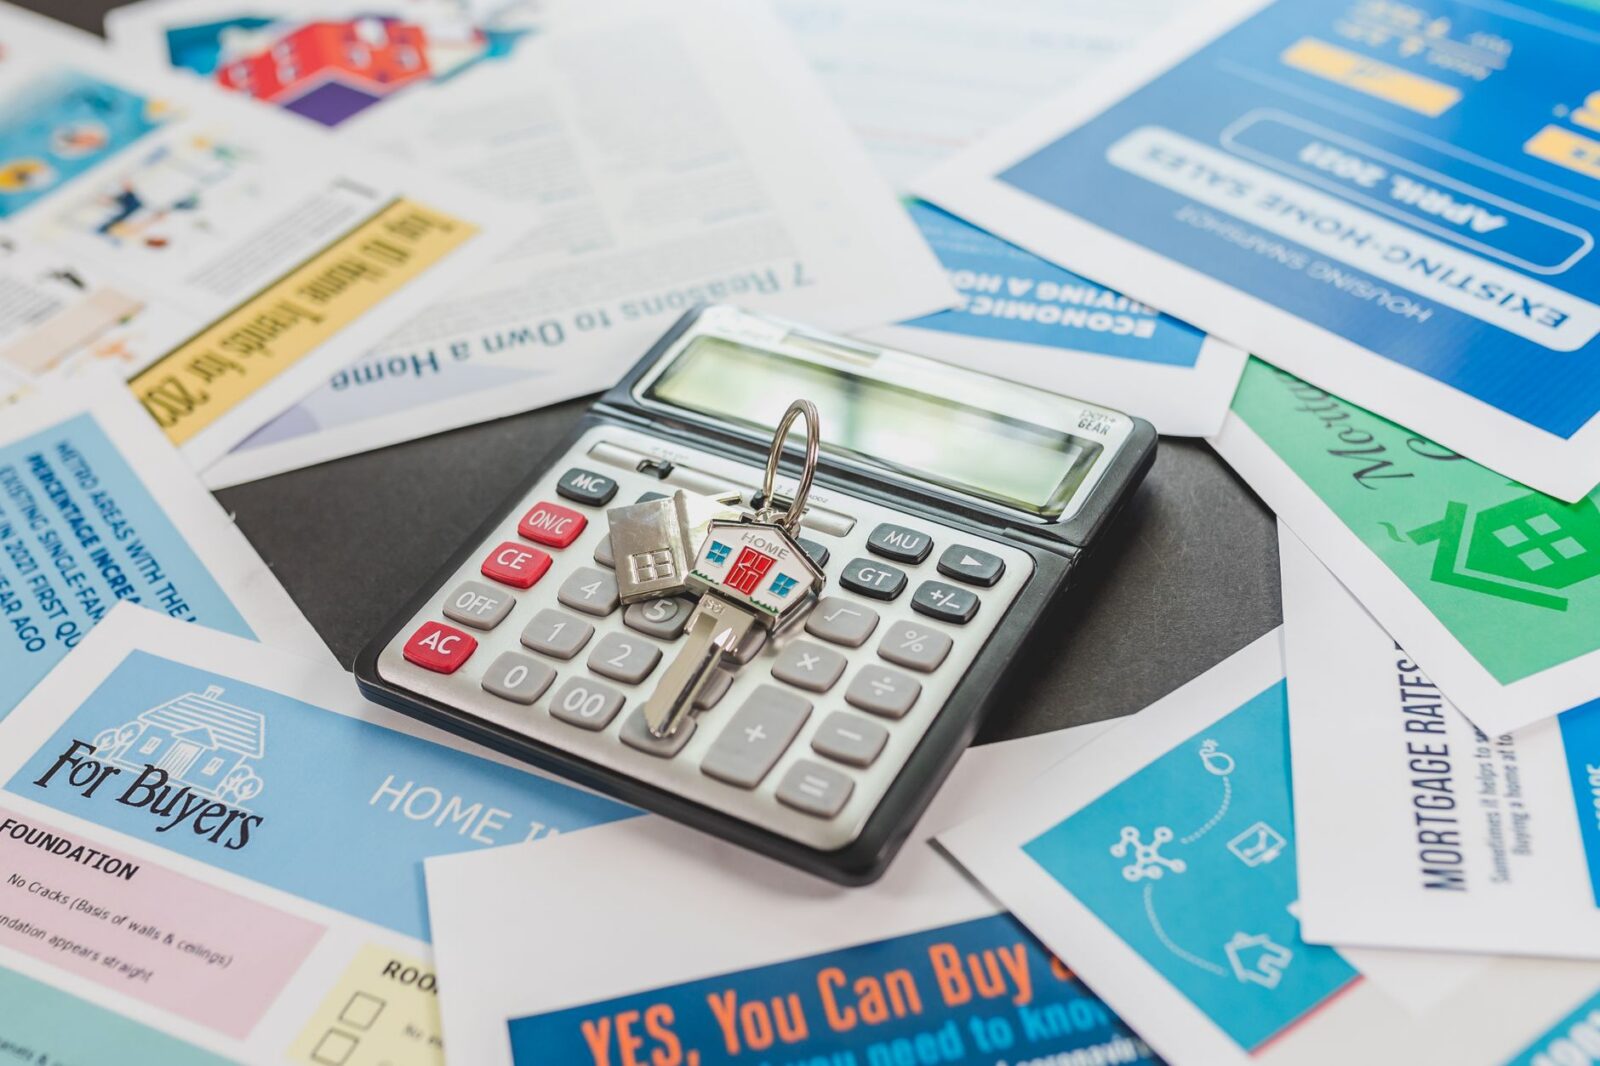
In a significant development for the U.S. housing market, 30-year mortgage rates have surpassed the 7% threshold for the first time in nearly two years. This milestone, reported by CBS News, marks a notable shift in borrowing costs that could have far-reaching implications for homebuyers and the broader economy.
The increase in mortgage rates comes in the wake of a series of economic indicators suggesting a tightening monetary policy by the Federal Reserve. As of September 25, 2026, the average rate for a 30-year fixed mortgage reached 7.01%, a level not seen since January 2025. This rise is attributed to the Fed’s ongoing efforts to combat inflation, which has remained stubbornly high, prompting concerns about affordability in the housing market.
Directly involved in this development are the Federal Reserve, which sets the benchmark interest rates, and mortgage lenders who adjust their rates in response to economic conditions. The decision to raise rates is part of a broader strategy to stabilize the economy, but it has immediate consequences for potential homebuyers. With higher borrowing costs, many buyers may be priced out of the market, leading to a slowdown in home sales and potentially affecting home prices.
The trigger for this increase can be traced back to the Federal Reserve’s recent meetings and statements indicating a commitment to maintaining higher interest rates until inflation is under control. The Fed’s decision to raise the federal funds rate has a direct impact on mortgage rates, as lenders adjust their rates based on the cost of borrowing.
This development is receiving heightened attention now due to its implications for the housing market, which has been recovering from the pandemic-induced slowdown. Analysts are closely monitoring how this increase will affect buyer sentiment and housing inventory. The National Association of Realtors has already expressed concerns that rising rates could lead to a decrease in home sales, which had been on an upward trajectory.
The significance of this rise in mortgage rates extends beyond the local market. Nationally, it could signal a cooling of the housing market, which has been characterized by rapid price increases and competitive bidding wars. As affordability becomes a pressing issue, the ripple effects could lead to a broader economic slowdown, impacting various sectors reliant on housing stability.
Looking ahead, it is realistic to anticipate further fluctuations in mortgage rates as the Federal Reserve continues to navigate its monetary policy. Homebuyers may need to adjust their expectations, and potential legislative measures could emerge to address housing affordability. The next Federal Reserve meeting, scheduled for October 2026, will be critical in determining the future trajectory of interest rates and, by extension, the housing market.
Source: Yahoo Finance UK

Mass Protests Erupt in Spain Over Housing Crisis Amid Early Election Announcement
Tens of thousands of Spaniards took to the streets today to protest...
 2 Mins read
Current Mortgage Refinance Rates Rise on October 6, 2026
The upward movement of mortgage refinance rates on October 6, 2026, signals...
2 Mins read
Spanish Prime Minister Calls Snap Elections Amid Housing Crisis Protests
The Spanish Prime Minister has announced snap elections in response to escalating...
2 Mins read
Spain’s Housing Crisis Takes Center Stage in Snap Election
The ongoing housing crisis in Spain has become a pivotal issue in...
2 Mins read
Leave a comment