AI’s Transformative Potential on Insurance Costs: Insights from McKinsey
MIAMI — October 3, 2026
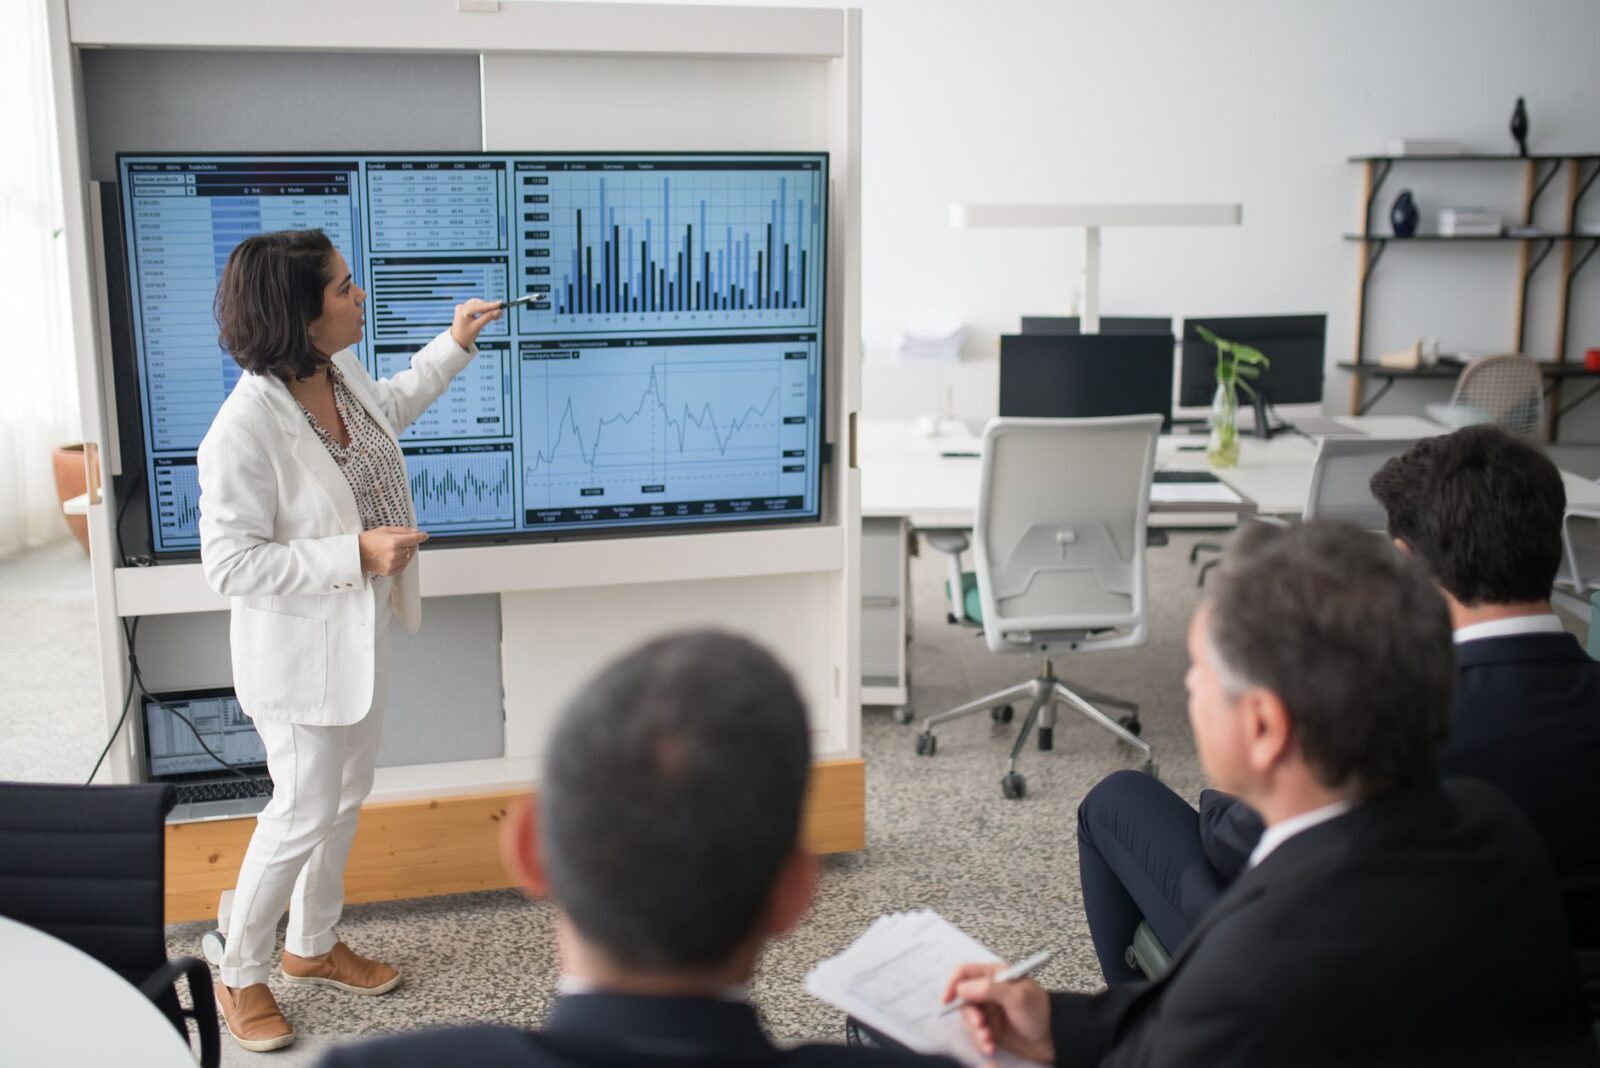
In a significant development for the insurance sector, a recent report by McKinsey & Company has underscored the transformative potential of artificial intelligence (AI) in reducing insurance costs, a challenge that has persisted despite two decades of digitization efforts. The report, published on October 3, 2026, sheds light on how AI could fundamentally alter market dynamics and consumer expenses in the insurance industry.
The McKinsey report indicates that while digitization has been a buzzword in the insurance sector for years, it has not led to the anticipated reductions in costs. Instead, the report suggests that AI technologies could provide the necessary tools to streamline operations, enhance risk assessment, and ultimately lower premiums for consumers. This assertion comes at a time when the insurance industry is grappling with rising operational costs and increasing competition.
Key players in the insurance market, including major firms such as Allstate, State Farm, and Progressive, are directly involved in this evolving landscape. These companies are now exploring AI-driven solutions to improve underwriting processes and claims management. The potential financial implications are substantial; McKinsey estimates that AI could reduce costs by up to 30% in certain segments of the insurance market, translating to billions of dollars in savings for both insurers and policyholders.
The impetus for this development stems from the growing recognition of AI’s capabilities in data analysis and predictive modeling. As insurers accumulate vast amounts of data, AI can help them make more informed decisions, thereby enhancing their competitive edge. This shift is particularly relevant as consumers increasingly demand personalized insurance products and services.
The timing of this report is critical, as the insurance industry faces mounting pressure to innovate and adapt to changing consumer expectations. With economic uncertainties and rising inflation affecting household budgets, the prospect of lower insurance costs through AI is garnering significant attention from both industry stakeholders and consumers alike.
From a broader perspective, the implications of AI’s integration into the insurance sector extend beyond mere cost savings. They touch on issues of consumer trust, regulatory compliance, and the ethical use of data. As AI technologies become more prevalent, regulators will need to ensure that these innovations do not compromise consumer rights or lead to discriminatory practices.
Looking ahead, the insurance industry is likely to witness a wave of AI-driven innovations in the coming years. Companies that successfully leverage AI will not only enhance their operational efficiencies but also redefine customer experiences. As firms begin to implement these technologies, we can expect to see pilot programs and collaborations between tech companies and insurers aimed at developing AI solutions tailored to specific market needs.
In conclusion, McKinsey’s report highlights a pivotal moment for the insurance industry, suggesting that AI could finally deliver the cost reductions that digitization has failed to achieve. As the sector evolves, stakeholders must navigate the complexities of technology adoption while ensuring that consumer interests remain at the forefront.
Source: LatestLY
Inflation Challenges the Pursuit of Financial Independence for Many Americans
Rising inflation is significantly impacting Americans' ability to engage in the Financial...
 2 Mins read
Iowa Governor Kim Reynolds Signs Expanded Tax Credits for $15 Billion Steel Plant
The approval of $1.36 billion in tax credits marks a significant economic...
2 Mins read
Iowa Approves $1.36 Billion Incentives for Foreign-Owned Steel Plant
The Iowa government has approved a substantial financial package to attract a...
2 Mins read


David Ellison Appoints Ynon Kreiz as Co-CEO of New Empire
The strategic appointment of Ynon Kreiz as co-CEO alongside David Ellison marks...
1 Mins read

Leave a comment