Federal Reserve Rate Hike Expected to Raise Mortgage and Credit Card Costs

MIAMI — September 21, 2026
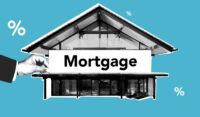
The Federal Reserve has announced a rate hike that is expected to lead to increased costs for mortgages and credit cards, a development that could have significant implications for consumers and the broader economy. This decision, made public on September 21, 2026, is part of the Fed’s ongoing strategy to manage inflation and stabilize economic growth.
The Federal Reserve’s decision to raise interest rates comes in the wake of persistent inflationary pressures that have affected various sectors of the economy. The hike is aimed at curbing inflation, which has been a growing concern for policymakers. As a result of this increase, consumers can expect to see higher interest rates on new mortgages and credit cards, making borrowing more expensive.
According to the Toledo Blade, the rate hike will likely lead to an increase in the average mortgage rate, which could rise by approximately 0.25% to 0.50%. For example, if the current average mortgage rate is around 3.5%, it could potentially increase to between 3.75% and 4.0%. This change could significantly impact homebuyers, particularly first-time buyers who may already be struggling with affordability in a competitive housing market.
Additionally, credit card interest rates are also expected to rise, which could further strain consumers’ finances. The average credit card interest rate, which currently hovers around 16%, may increase to 16.25% or higher, depending on the specific terms of individual credit agreements. This increase could lead to higher monthly payments for consumers who carry balances on their credit cards.
The implications of this rate hike are far-reaching. Locally, in Miami and across the United States, the increase in borrowing costs could dampen consumer spending, which is a critical driver of economic growth. Nationally, higher mortgage rates could slow down the housing market, as potential buyers may be deterred by increased costs. Regionally, states with higher concentrations of variable-rate loans may feel the impact more acutely.
As the Federal Reserve continues to navigate the complexities of inflation and economic recovery, the focus will be on how these rate changes affect consumer behavior and overall economic stability. Analysts predict that if inflation persists, further rate hikes may be necessary, leading to a cycle of increasing costs for consumers.
In the coming weeks, financial institutions will likely adjust their rates in response to the Fed’s decision, and consumers should prepare for the financial implications of these changes. Homebuyers and those considering significant purchases should closely monitor interest rates and consider locking in rates before they rise further.
Source: Toledo Blade




Xi Jinping’s High-Stakes Visit to the U.S. Confirmed for September 2026
Chinese President Xi Jinping's upcoming visit to the United States marks a...
 2 Mins read

SoftBank Launches Over $11 Billion Bond Sale to Fund OpenAI Investment
SoftBank's significant bond sale reflects confidence in the future of artificial intelligence...
2 Mins read
Positive US-China Talks Boost Stock Market Ahead of Trump-Xi Meeting
Successful discussions between US and Chinese officials signal potential economic stabilization, impacting...
2 Mins read


Bessent’s Meeting with China Vice Premier He Lifeng Signals Potential Shift in US-China Relations Ahead of Trump-Xi Summit
The recent meeting between Bessent and China’s Vice Premier He Lifeng is...
2 Mins read

Leave a comment